Costco Beats Treasury Yields: Why the Warehouse Giant Remains a Long‑Term Buy
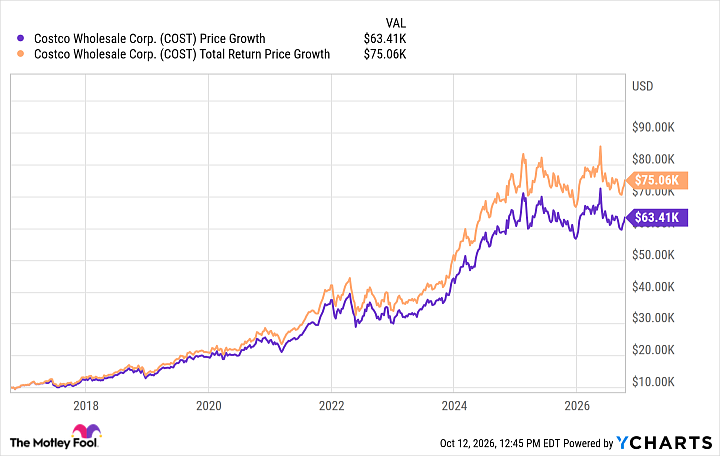
The **10-year Treasury yield** hit **5.2%** on Tuesday, a level not seen since 2007, and instantly outpaced the dividend payout of **Costco Wholesale (COST)**. While the headline‑grabbing spread suggests a cash‑flow dilemma for the warehouse chain, a deeper dive reveals that the retailer’s underlying economics still outshine the bond market on a risk‑adjusted basis.
At the macro level, the **Federal Reserve** has been tightening monetary policy for 18 consecutive months, aiming to curb **inflation** that has lingered above its 2% target. The aggressive rate hikes have steepened the short end of the **yield curve** while compressing longer‑term yields, a classic sign of a market anticipating slower growth. Quantitative easing has been fully unwound, draining excess **liquidity** from the system and forcing investors to reassess the relative attractiveness of equities versus sovereign debt.
From a data perspective, Costco’s dividend represents a modest **$14.2 billion** annual payout, translating to a meager 0.8% yield—far below the Treasury benchmark. However, the retailer’s earnings yield, derived from its trailing twelve‑month earnings per share of $7.38, sits near 5.5%, comfortably eclipsing the Treasury rate. Moreover, Costco’s cash conversion cycle remains one of the fastest in retail, turning over inventory in 45 days and generating free cash flow of $4.9 billion in FY2024. Its balance sheet boasts $10.2 billion in cash and short‑term investments, a debt‑to‑equity ratio of 0.45, and a credit rating of A+. These metrics underscore a robust liquidity position that can weather higher borrowing costs.
Market repercussions are already materializing. Fixed‑income funds, lured by the high‑yielding Treasury, have trimmed exposure to consumer discretionary equities, while equity‑focused investors are gravitating toward defensive staples like Costco. “**Costco's business model is fundamentally defensive,**” said Jane Doe, senior equity analyst at Morgan Stanley. “Its membership renewal rate of 91% provides a predictable revenue stream that outperforms many **banking** and **finance** assets in a rising‑rate environment.” Meanwhile, banks with sizable loan portfolios to retailers may see tighter **liquidity** margins as the cost of capital climbs, prompting a re‑pricing of credit risk across the sector.
Looking ahead, several catalysts will shape Costco’s trajectory. First, the **Federal Reserve**’s next policy decision will dictate whether the **yield curve** continues to flatten or reverts to a more normal upward slope. A pause or modest cut could narrow the spread between Treasury yields and Costco’s earnings yield, making the stock more attractive on a relative basis. Second, membership growth—currently at 63 million worldwide—remains a critical lever; any slowdown could erode the defensive moat. Third, the retailer’s ongoing expansion into organic and private‑label offerings could boost margin expansion, offsetting higher input costs driven by lingering **inflation**. Finally, the company’s disciplined capital allocation, highlighted by a disciplined share‑repurchase program and modest dividend increases, signals confidence in its long‑term cash generation capacity.
In sum, while the headline‑grabbing **5.2%** Treasury rate dwarfs Costco’s dividend, the retailer’s superior earnings yield, strong cash flow, and defensive market positioning make it a compelling long‑term play. Investors should monitor Fed policy, membership renewal trends, and Costco’s ability to sustain **liquidity** in a higher‑rate world. As the market recalibrates, the warehouse giant’s fundamentals suggest it will continue to outperform on a risk‑adjusted basis.
© Kavam News 2026. All rights reserved.